Your Profit and Loss Statement Tells a Story Before You Enter the Room
Most business owners look at their profit and loss statement and go straight to one line: net profit. I understand why. You want to know whether the business made money.
A banker looks at that same report differently. The bottom line matters, but it is not the only thing being reviewed. A banker is also looking for patterns. Is revenue steady? Are margins holding? Are expenses controlled? Can the business reasonably handle another payment?
Here is the part many owners do not realize: your financial statements start telling a story before you have the chance to explain anything. If the story on the page does not match the story in your head, you need to understand why.
A lending decision is never based on the P&L alone. The bank may also review the balance sheet, cash flow, tax returns, existing debt, credit history, and other information. But the P&L is one of the first places a banker looks to understand how the business earns money and how well it is being managed.
From Intention to Perspective
Last month, we talked about becoming more intentional about who guides your business financially. This month, I want you to look at your numbers from the other side of the desk.
You know what happened inside the business. You remember the delayed customer payment, the employee who left, the equipment repair, and the investment you expect to pay off next quarter. A banker does not begin with that history. A banker begins with the report.
That does not make either view wrong. It means your explanation needs to be supported by the numbers.
What the Owner May See
Revenue increased, so the business is growing.
We had one unusually expensive month.
The business showed a profit.
I know why the numbers changed.
Next year will be better.
What the Banker May Ask
Did profit and cash flow improve with that growth?
Was it truly unusual, or is it becoming a pattern?
Is the profit consistent enough to support current obligations and another payment?
Do the reports and supporting records back up that explanation?
What in the history and current plan makes that expectation reasonable?
What a Banker Notices Before the Bottom Line
A lender is not simply looking for a positive number at the bottom of the page. The report is being reviewed for signs of stability, control, and the ability to manage another financial obligation.
1 Revenue Patterns
Revenue matters, but the pattern matters too. Is it growing steadily, staying flat, or jumping up and down? One strong month may look encouraging, but it does not carry the same weight as a consistent trend.
2 Gross Profit and Margin
Revenue can increase while the business becomes less profitable. If labor, materials, subcontractors, or other direct costs rise faster than sales, gross margin gets weaker. A banker may ask whether your pricing has kept up with the true cost of delivering the work.
3 Operating Expenses
Expenses tell a banker how the business is being managed. Are payroll and overhead rising faster than revenue? Are there large categories that are not clear? Are personal expenses mixed into the business? The goal is not to make every expense disappear. The goal is to show that spending is controlled and connected to the business.
4 Consistency of Profit
One profitable year is helpful. Several years of stable profit tell a stronger story. If profit changes sharply, be ready to explain what happened. Was it a one-time expense? Did a major customer leave? Did the company invest in growth? A clear explanation matters, but the books still need to support it.
5 The Quality of the Books
Clean books communicate more than accuracy. They show control. Duplicate accounts, uncategorized transactions, negative expense balances, and reports that keep changing make the business harder to evaluate. A healthy company can still create concern when the records are unclear.
6 Room for Another Payment
The banker ultimately needs to understand whether the business can repay what it borrows. The P&L helps show operating performance, but it does not show the full picture. Loan principal, available cash, assets, liabilities, owner distributions, and working-capital needs appear elsewhere. This is why the P&L must be reviewed alongside the other financial statements.
The Same Growth Story Can Look Very Different
Imagine a service business whose revenue increased from $800,000 to $1 million. The owner sees a $200,000 increase and feels confident that the company is growing.
Now look a little closer. Direct labor and materials increased faster than revenue. Gross margin fell. Administrative payroll increased. The owner took larger distributions, and several vendors were paid later than usual. The business still showed a profit, but it had less room to absorb a slow month or another fixed payment.
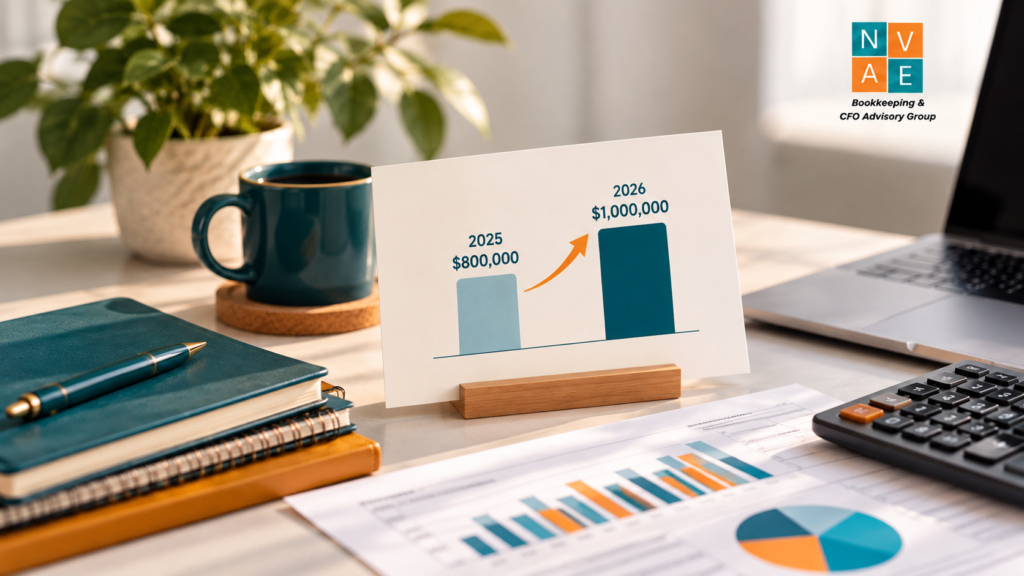
The owner sees growth. The banker sees growth that may be putting pressure on profit and cash.
That does not mean an automatic no. It means you need to explain what changed, why it changed, and what you are doing next. Accurate numbers make that explanation stronger.
What the P&L Says at Each Business Stage
Stage 1 Clean Books Foundation
In the early years, the P&L may still have inconsistent categories, owner purchases, missing costs, or reports that are prepared only at tax time. The owner knows the business is busy but may not know which services, products, or customers are actually profitable.
At this stage, start with reliable bookkeeping and a monthly review. Before the report can tell a useful story to a lender, it needs to tell an accurate story to you.
→ Focus: Accurate records, clear categories, and consistent monthly reporting
Stage 2 Monthly Money Insights
The books are current and the business may be profitable, but now you are considering a line of credit, another employee, new equipment, or a larger space. The P&L needs to do more than document the past. It needs to help you understand trends, margins, fixed costs, and how much financial pressure the business can carry.
This is the time to review the business before the lender does. Waiting until an application is already moving creates unnecessary pressure.
→ Focus: Profit trends, stable margins, expense control, and readiness for another obligation
Stage 3 CFO Level Growth
As the company grows, the questions become more detailed. Lenders, investors, buyers, and strategic partners may ask for multi-year statements, year-to-date comparisons, forecasts, debt schedules, and explanations for unusual changes.
At this stage, financial reporting becomes part of leadership. You should be able to explain where the results came from, what risks are developing, and how your plans connect to the financial capacity of the business.
→ Focus: Coordinated reporting, documented explanations, forecasting, and decision-ready information
A Note from Rita
During my years in banking, I learned that a financial statement starts communicating before the owner has the opportunity to explain it. A banker rarely looks at one number in isolation. We look for consistency, credibility, and signs that the owner understands how the business makes money.
That is why I encourage business owners to review their P&L before they need financing. Do not wait until the application is in progress to discover that revenue increased while margins declined, expenses were placed in the wrong categories, or the report does not match the story you expected it to tell.
You should be able to explain the major changes clearly: what happened, why it happened, whether it is temporary, and what you are doing next. That preparation helps with more than banking. It helps you run the business better.
The Perspective Check
Before you share your P&L with a lender or make a major financial decision, ask yourself:
- Are revenue and profit moving in the same direction?
- Are gross margins stable, improving, or declining?
- Can I explain the major month-to-month or year-to-year changes?
- Are expenses categorized clearly and consistently?
- Does the report separate business activity from personal spending?
- Are the books current enough to support the story I am telling?
- What would a lender need beyond the P&L, including the balance sheet, cash flow, tax returns, and debt information?
- If I saw these numbers for the first time, what would I question?
You do not need perfect numbers. You need accurate numbers, a clear explanation, and a real understanding of what is happening inside the business.
Where NAVE Bookkeeping & CFO Advisory Group Fits In
At NAVE, we help business owners create financial reports that are accurate, understandable, and useful before an important decision is already on the table.
Through bookkeeping, we build the clean financial foundation a lender, investor, buyer, or owner needs to evaluate the business. Through CFO advisory, we help owners understand trends, watch margins and cash flow, prepare for financing conversations, and see how today’s choices may affect tomorrow’s options.
We do not promise loan approval, and we do not replace the lender’s underwriting process. We help you enter the conversation with cleaner information, stronger questions, and a better understanding of the story your business is telling.
Book Recommendation
Financial Intelligence for Entrepreneurs by Karen Berman and Joe Knight
Many business owners receive financial statements without feeling confident about what the reports are really saying. This book explains the income statement, balance sheet, cash flow statement, and the judgment behind the numbers in practical language for non-financial owners and leaders.
It connects directly to this month’s theme of perspective. A banker, investor, buyer, and business owner may look at the same report for different reasons. The more comfortable you become with the numbers, the better prepared you are to understand their questions and explain your results.
Straightforward guidance. Numbers you can use.
Final Thought
Your P&L is more than a list of revenue and expenses. It is part of the story your business tells about stability, profit, management, and readiness for what comes next.
You already know the story from the inside. Now learn to read it from the outside. Look at the trends. Question the margins. Explain the changes. Make sure the report supports what you believe about the business.
A banker should not be the first person to help you notice what your P&L is saying.
Would Your P&L Tell the Story You Expect
If your reports are current but you are unsure what they communicate to a lender, investor, or future buyer, NAVE Bookkeeping & CFO Advisory Group can help you review the story behind the numbers.
Are you ready to see your business from the other side of the desk?
Schedule a complimentary Financial Clarity Call with NAVE. We will help you identify what your P&L is saying, what may be missing, and what deserves your attention before an important financial conversation begins.
NAVE Bookkeeping & CFO Advisory Group — Guiding businesses through every stage of growth with expert financial foundations and CFO-level insight.
Frequently Asked Questions
Does a strong P&L guarantee that a business loan will be approved?
No. A strong P&L helps, but lenders usually review the full financial picture. That may include the balance sheet, cash flow, tax returns, existing debt, credit history, collateral, and the purpose of the loan. Requirements vary by lender and loan type.
Why can a business show a profit and still have cash problems?
Profit and cash are not the same. Customers may not have paid yet, cash may have been used for equipment or loan principal, or money may be tied up in inventory and other working-capital needs. Reviewing the balance sheet and cash flow with the P&L helps explain the difference.
When should I review my P&L before applying for financing?
Start before you need the money. Review the report regularly so you have time to correct bookkeeping issues, understand changes in margins or expenses, and prepare clear explanations. Waiting until an application is underway limits your options.
Note: Lending requirements vary by lender, loan type, and borrower. This article is educational and does not guarantee financing or approval.